Skip to content
Advertisement
Salesforce shares fall 3% on soft revenue outlook, AI concerns persist

Salesforce shares fall 3% on soft revenue outlook, AI concerns persist

Despite beating Q2 estimates and posting 120% AI revenue growth, Salesforce's underwhelming Q3 guidance is spooking investors worried about AI's slow payoff.

Salesforce beat its quarterly revenue estimates and grew its AI business by 120% year-over-year. The stock still dropped.

Shares of the CRM giant fell between 3% and 8% in post-market trading on September 4 after the company issued Q3 revenue guidance that landed below Wall Street expectations. The forecast range of $10.24 to $10.29 billion, while representing continued growth, wasn’t enough to satisfy investors already jittery about AI’s uncertain return on investment.

Fiscal Q2 2026 revenue hit $10.2 billion, a 10% year-over-year increase that cleared analyst estimates. The company even raised its full-year revenue outlook.

Advertisement

The AI paradox: growing fast, monetizing slow

Data Cloud and AI annual recurring revenue climbed to $1.2 billion, representing a 120% jump from the same period last year. The company’s Agentforce initiative has racked up thousands of paid customer deals.

But $1.2 billion in AI ARR against a company generating over $10 billion per quarter tells you something important. The AI revenue engine is still a rounding error relative to the broader business.

The concern among analysts isn’t merely about the pace of monetization. It’s about whether generative AI and autonomous agents could eventually replace the kind of traditional CRM software that built Salesforce into a $200B-plus company in the first place.

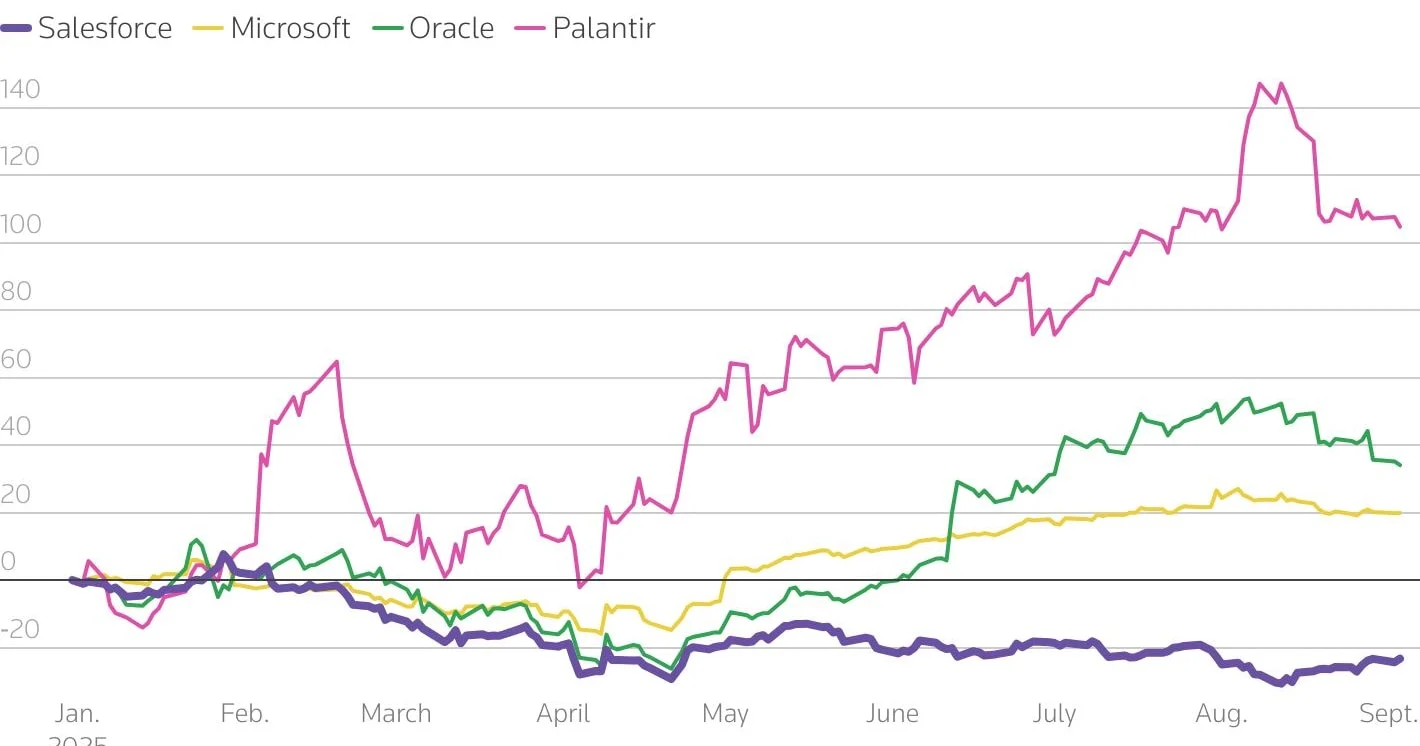
A year investors would rather forget

As of September 4, the stock has declined as much as 27% to 30% year-to-date.

Salesforce raised the low end of its FY26 revenue guidance to a range of $41.1 to $41.3 billion, implying 8.5% to 9% year-over-year growth. It also expanded its share buyback program.

What this means for investors

Enterprise companies are being told they must invest in AI or die. But the customers buying those AI tools are themselves being cautious with spending, creating a mismatch between the pace of investment and the pace of adoption.

At $1.2 billion in annual recurring revenue, Salesforce’s AI business is already larger than many standalone SaaS companies. Agentforce has between 6,000 to 12,500 paid customer accounts by late 2025. Salesforce needs those deals to expand rapidly within customer organizations to move the needle on its overall revenue mix.

Salesforce Inc. (CRM) price

Full chart and stats

Loading chart…

Market cap
$188.6B (shares as of 2026-08-20)
P/E (trailing)
21.0 (EPS to 2026-07-31)
Annual revenue
$41.5B USD (FY ended 2026-01-31) 10-K
Annual revenue growth
+9.6% (FY ended 2026-01-31 vs FY ended 2025-01-31) 10-K
Annual net income
7,457,000,000 USD (FY ended 2026-01-31, attributable to the company) 10-K
Annual operating margin
20.1% (FY ended 2026-01-31)
Forward P/E
Unavailable: no dated forecast source

Gloria daily close for session Oct 30, 2026. Market cap and trailing P/E use this close with the SEC share total and trailing diluted earnings, each dated next to its figure. Annual revenue, revenue growth, net income and margin show their own fiscal period and link the 10-K. Current context may postdate this article.

Salesforce Inc. and its peers

Company PriceMarket capP/E (trailing)Forward P/EAnnual revenue (USD)Annual revenue growthAnnual net income (USD)Operating margin
Salesforce Inc. CRM · Price dated Oct 30, 2026 · tokenized CRMx $229$188.6B21.0Unavailable$41.5BFY ended 2026-01-31 · 10-K+9.6%FY ended 2026-01-31 vs 2025-01-31 · 10-K7,457,000,000FY ended 2026-01-31, attributable to the company · 10-K20.1%FY ended 2026-01-31
Shopify Inc. SHOP · Price dated Oct 30, 2026 $157Unavailable106.4Unavailable$11.6BFY ended 2025-12-31 · 10-K+30.1%FY ended 2025-12-31 vs 2024-12-31 · 10-K1,231,000,000FY ended 2025-12-31, attributable to the company · 10-K12.7%FY ended 2025-12-31
CrowdStrike Holdings Inc. CRWD · Price dated Oct 30, 2026 · tokenized CRWDx $250$256.4BNot meaningfulLoss, diluted EPS −0.45
to 2026-07-31 · SEC filing
Unavailable$4.8BFY ended 2026-01-31 · 10-K+21.7%FY ended 2026-01-31 vs 2025-01-31 · 10-K−162,502,000FY ended 2026-01-31, attributable to the company · 10-K−6.1%FY ended 2026-01-31
ServiceNow Inc. NOW · Price dated Oct 30, 2026 $105$109.1B75.6Unavailable$13.3BFY ended 2025-12-31 · 10-K+20.9%FY ended 2025-12-31 vs 2024-12-31 · 10-K1,748,000,000FY ended 2025-12-31, attributable to the company · 10-K13.7%FY ended 2025-12-31

Missing figures stay unavailable. Forward P/E requires a dated source. Annual revenue, revenue growth, net income and margin come from each company's own 10-K, in US dollars, and each row shows that fiscal year. Revenue growth compares the fiscal year with the prior year stated in the same 10-K. Net income is the full year amount attributable to the company, or available to common stockholders where the filing states only that, or consolidated net income. Each row names its basis. Trailing P/E reads "Not meaningful" when the dated trailing diluted EPS is a loss or zero. An operating margin appears only when the filing states both the operating income and the revenue for the same year.

Sources: SEC filings, Gloria daily closes and CoinGecko. Oldest record refresh: Oct 31, 2026, 3:51 AM EDT. Refresh is not a price or filing date. Each row shows its price date and its annual fiscal period. Peers use industry code and company size, or editorial selection. Market cap multiplies that row price by the company share total the latest SEC filing states for every share class together. Trailing P/E divides it by trailing diluted earnings from SEC filings. Rolled earnings per share are approximate because share counts can change between periods. Both appear only when the SEC data carries its date, so they are estimates at one price date, not synchronized filing valuations. Not investment advice.

Disclosure: This article was edited by Editorial Team. For more information on how we create and review content, see our Editorial Policy.

More in AI

See all
Previous storyMiniMax teases M3 model with 15.6x faster decoding speed boost