+15.1% (FY ended 2025-12-31 vs FY ended 2024-12-31) 10-K
Annual net income
132,170,000,000 USD (FY ended 2025-12-31, attributable to the company) 10-K
Annual operating margin
32.0% (FY ended 2025-12-31)
Forward P/E
Unavailable: no dated forecast source
Gloria daily close for session Oct 29, 2026. Market cap and trailing P/E use this close with the SEC share total and trailing diluted earnings, each dated next to its figure. Annual revenue, revenue growth, net income and margin show their own fiscal period and link the 10-K. Current context may postdate this article.
Alphabet Inc. and its peers
Company
Price
Market cap
P/E (trailing)
Forward P/E
Annual revenue (USD)
Annual revenue growth
Annual net income (USD)
Operating margin
Alphabet Inc.
GOOGL · Price dated Oct 29, 2026 · tokenized GOOGLx
3,333,751,000FY ended 2025-12-31, attributable to the company · 10-K
75.8%FY ended 2025-12-31
Missing figures stay unavailable. Forward P/E requires a dated source. Annual revenue, revenue growth, net income and margin come from each company's own 10-K, in US dollars, and each row shows that fiscal year. Revenue growth compares the fiscal year with the prior year stated in the same 10-K. Net income is the full year amount attributable to the company, or available to common stockholders where the filing states only that, or consolidated net income. Each row names its basis. Trailing P/E reads "Not meaningful" when the dated trailing diluted EPS is a loss or zero. An operating margin appears only when the filing states both the operating income and the revenue for the same year.
Sources: SEC filings, Gloria daily closes and CoinGecko. Oldest record refresh: Oct 29, 2026, 12:56 PM EDT. Refresh is not a price or filing date. Each row shows its price date and its annual fiscal period. Peers use industry code and company size, or editorial selection. Market cap multiplies that row price by the company share total the latest SEC filing states for every share class together. Trailing P/E divides it by trailing diluted earnings from SEC filings. Rolled earnings per share are approximate because share counts can change between periods. Both appear only when the SEC data carries its date, so they are estimates at one price date, not synchronized filing valuations. Not investment advice.
Token vs underlying stock
Current comparison for GOOGL. Historical observations may postdate this article.
Split-adjusted regular-session stock closes from the existing Gloria shared history, paired only with an observed token price within 45 minutes of 16:00 New York time. Up to 60 matched sessions. No interpolation or missing-date fill. Weekends and known early closes are omitted. Token units are not adjusted for issuer multipliers or dividend treatment. This compares quoted prices, not fair value, executable premiums or arbitrage returns. Solid line: token. Dashed line: stock. Exact quote times and values appear below. Historical observations. Retrieval refers to the token source. Token quote times use UTC. The fixed cohort shows its oldest member fetch.
Alphabet token vs Alphabet stock: exact source values
Quoted token and share units can have different rights, multipliers and dividend treatment. This is not an executable premium or arbitrage signal.
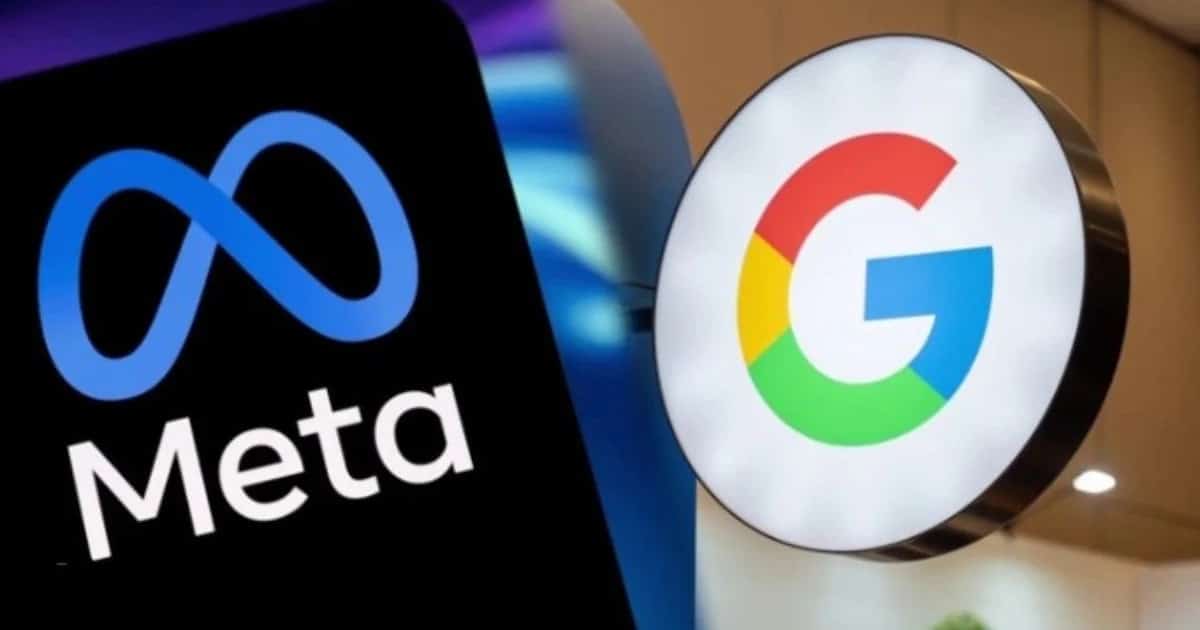
A California state judge on June 10 rejected motions from Meta Platforms and Alphabet’s Google seeking a new trial in what has become one of the most consequential tech liability cases in recent memory. The ruling keeps intact a $6 million jury verdict that found both companies negligent for designing platforms, specifically Instagram and YouTube, that fueled addiction in a child plaintiff identified as K.G.M.
The verdict, originally handed down on March 25, 2026, marked the first time a jury held social media companies financially responsible not for what users posted, but for how the platforms themselves were engineered.
What the jury found, and what the judge preserved
The original trial centered on K.G.M., also referred to as Kaley, who alleged that compulsive use of Instagram and YouTube beginning in childhood led to depression and anxiety. Her legal team argued that specific design features, things like infinite scrolling, autoplay, and push notifications, were deliberately built to maximize engagement at the expense of young users’ mental health.
The jury agreed. It apportioned 70% of the blame to Meta, ordering the company to pay $4.2 million. Google was tagged with the remaining 30%, or $1.8 million.
Both companies filed motions for a new trial, effectively asking the court to give them a do-over. The judge said no.
Why this case is different from everything before it
Tech companies have faced lawsuits over user-generated content for years and have largely won, shielded by Section 230 of the Communications Decency Act, which generally protects platforms from liability for what users post. This case sidestepped that defense entirely.
AI, tech, and the markets they move—in one daily briefing.
Daily. Free. Join 34,000+ readers across crypto, finance, and policy.
Instead of arguing that harmful content appeared on Instagram or YouTube, the plaintiff’s attorneys focused on product design. The claim wasn’t that Meta and Google failed to moderate content. It was that the platforms were built to be compulsive, and that children were particularly vulnerable to those mechanics.
Similar cases are already moving through courts nationwide. A related challenge in Vermont recently reached the US Supreme Court, which declined to hear it. That refusal to intervene left lower court rulings in place.
Both companies plan to appeal
Neither Meta nor Google is accepting the outcome quietly. Both have stated their intention to appeal the verdict, arguing that the complex nature of teen mental health issues cannot be pinned on their platforms alone.
But the jury wasn’t asked to find that Instagram and YouTube were the only cause of Kaley’s mental health struggles. It was asked whether the companies’ design choices were a substantial contributing factor. It concluded they were.
What this means for investors
Hundreds of similar lawsuits are pending across the US, many consolidated into multidistrict litigation. If the product-design theory of liability survives appeals, each case becomes a potential payout.
For Meta specifically, Instagram has been the subject of internal research, some of it leaked, suggesting the company was aware of negative mental health effects on teen users.
Google’s exposure centers on YouTube’s autoplay and recommendation algorithms, and the company has already made some changes to its youth-facing features.
Disclosure: This article was edited by Editorial Team. For more information on how we create and review content, see our Editorial Policy.